
Rocket Mortgage
- Rating
- 4.7
- Downloads
- 1.00M
- Content Rating
- Everyone
Rocket Mortgage - Screenshots
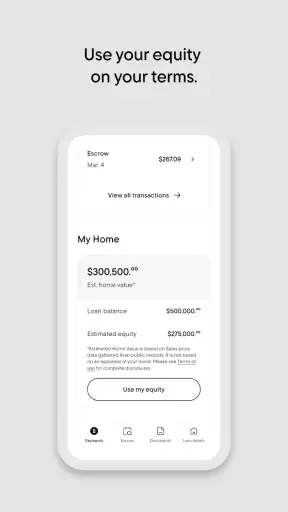
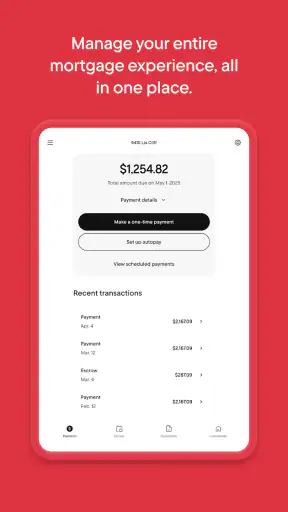
Pros
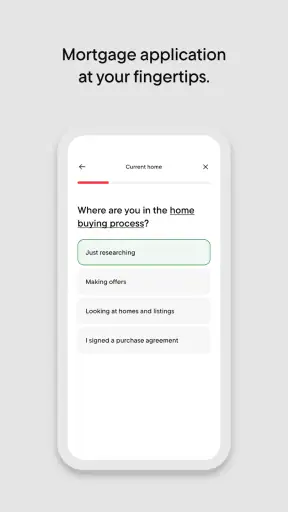
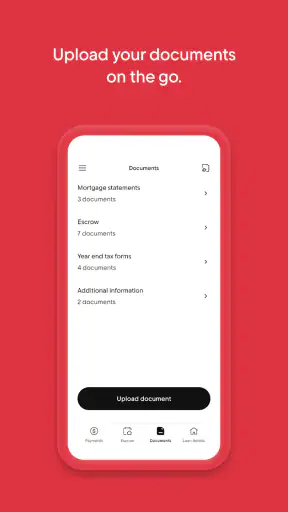
- Fully digital mortgage application with convenient document uploads.
- Clear loan calculators help estimate monthly payments and borrowing power.
- Multiple mortgage options suit different buyer and refinancing situations.
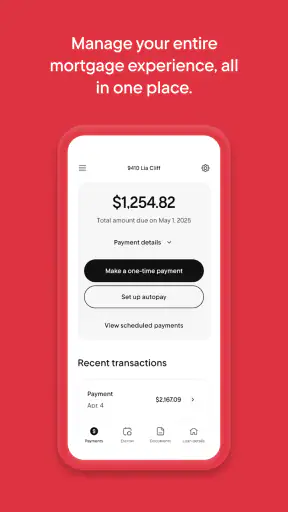
- Rate and payment updates are easy to review through the mobile dashboard.
- Helpful educational resources explain key steps of the mortgage process.
Cons
- Availability and loan terms vary by state and borrower qualifications.
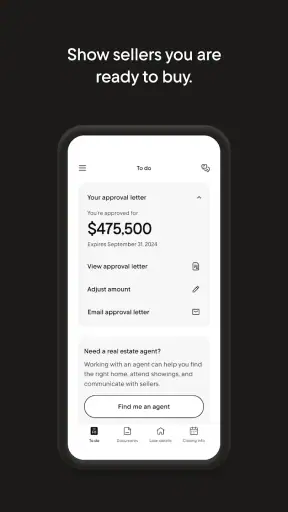
- Prequalification does not guarantee final approval or the displayed rate.
- Some users may prefer speaking with a local
- in-person loan officer.
- Mortgage applications require sensitive financial and personal information.
- Closing timelines can still depend on third parties and document processing.
Rocket Mortgage - Description
- App Name
- Rocket Mortgage
- Package Name
- com.quickenloans.myql
- Developer
- Rocket Mortgage
- Category
- Finance
- Last Updated
- Aug 6, 2011
- Version
- 10.35.0
Managing a mortgage is rarely a one-person household task. Even when one borrower handles the formal account, another person may need to check the balance, understand an upcoming payment, or coordinate a decision about the home. I found Rocket Mortgage most useful in that everyday space: it puts mortgage information into a mobile finance app instead of making every small question depend on a computer or a phone call.
Rocket Mortgage is a free finance app from Rocket Mortgage for Android and iOS users. It is rated for Everyone, which fits the practical nature of the tool, although the financial decisions made through it are obviously matters for adults. The app has a 4.7 average from around 32 thousand ratings, and more than a million people have installed it. Those figures suggest that it is not a niche companion for a narrow group of borrowers, but I would still judge it by how well it fits your household routine rather than by popularity alone.
How Rocket Mortgage works in a shared household
My first impression is that the app makes the mortgage feel more visible. A home loan can become something one person quietly manages while everyone else only hears about it when a payment is due. Having a dedicated mobile view encourages more regular awareness. I can imagine opening it while discussing the monthly budget, checking a detail before contacting the lender, or reviewing the account while away from a desktop.
That convenience matters most when household responsibilities are divided. One person may organize bills, while another tracks income, savings, or plans for the property. The app can support that conversation by giving the account holder a quick place to review mortgage-related information. It does not replace an agreed household budget, but it can reduce the need to rely on memory or pass around screenshots.
A realistic example would be a couple preparing their monthly finances on a Sunday evening. The person who normally pays the mortgage opens the app and checks the account before the two of them decide how much can go toward utilities, groceries, or a repair. The other person does not need to take over the account to participate in the discussion. The useful part is not simply speed; it is having the relevant mortgage context available at the moment a decision is being made.
There is also a practical benefit when plans change during the day. If you are arranging a move, reviewing household costs, or speaking with a professional about the property, having mobile access can be more convenient than waiting until you are back at a computer. I would not treat the phone as the only place to make an important financial decision, but it is a helpful first stop for orientation.
The important boundary is that a shared home does not automatically mean a shared account. I would not hand an unlocked phone to another household member and assume that casual access is harmless. Mortgage information is sensitive, and the app should be used by the person whose account it is, within the account and device arrangements they control. If two adults need regular visibility, they should agree on a safe way to coordinate rather than casually sharing credentials.
Setting it up without blurring account boundaries
The setup is best approached as an account-management task, not as a family dashboard. I would begin with the borrower who is responsible for the mortgage, make sure that person can access the account, and then decide how the household will discuss information afterward. That small distinction prevents a common mistake: treating convenience as permission for everyone to use the same login.
On a shared tablet or family phone, I would be especially careful. A mortgage app is not like a recipe app that can be left open for anyone to browse. Before using it on a device that other people handle, I would check whether the device itself is protected and whether the app remains visible after use. I would also avoid leaving account screens open while passing the phone to someone else.
I found this boundary useful because it keeps responsibility clear. The app is a tool for the mortgage account holder, while household coordination can happen through conversation, notes, or a separate budgeting routine. That may sound less seamless than a shared family finance platform, but it is more sensible for a loan account where personal access and financial privacy matter.
Another practical tip is to use the app at deliberate moments instead of repeatedly checking it out of anxiety. A short review before the household budget meeting is more useful than opening it every time you wonder about the loan. This turns mobile access into a routine: check the account, discuss what matters, and close the app when the conversation is finished.
The app is not a substitute for reading formal loan documents. If a question involves the exact meaning of a mortgage term, a change in obligations, or a decision with long-term consequences, I would use the app to locate the relevant account context and then confirm the matter through the appropriate official channel. Mobile convenience is valuable, but it should not encourage rushed interpretations.
Coordinating payments and household decisions
Rocket Mortgage works best when it is part of a larger household process. I would pair it with a simple budget calendar that records when the mortgage is reviewed, when other major bills are due, and who is responsible for each task. The app can provide the mortgage side of that conversation, while the calendar prevents one person from becoming the only source of financial memory.
This is particularly useful in households where responsibilities change from month to month. Someone may handle payments while another person is traveling, caring for a child, or dealing with work deadlines. A shared discussion about the account can make the transition less confusing, but I would still keep the actual account access with the authorized user unless the lender has established another arrangement.
One non-obvious strength is that mobile access can improve the timing of questions. Instead of vaguely saying, “I think the mortgage is fine,” the account holder can review the current information before asking what needs clarification. That produces a better conversation with a partner and, when necessary, a more focused conversation with the mortgage provider.
There is a trade-off, though. A specialized mortgage app is naturally narrower than a full household finance app. It may be better for keeping the home loan in view, while a budgeting application may be better for combining income, credit cards, savings, utilities, and spending categories. I would not expect Rocket Mortgage to become the household’s complete financial command center simply because it is convenient.
Compared with checking a mortgage through a general banking app, a dedicated service can feel more direct because the home loan is the central subject rather than one account among many. On the other hand, a bank app may be more convenient for someone who wants all balances and payments in one place. The better choice depends on whether your main problem is mortgage access or overall financial organization.
Compared with using a desktop browser, the mobile app is more suitable for quick checks and short conversations. A larger screen may still be preferable when reviewing several documents, comparing figures, or working through a complicated decision. I see the app as the convenient layer around mortgage management, not as a reason to abandon every other way of reviewing important information.
Age, trust, and who should use it
The Everyone age rating means the app is presented as suitable for a broad audience, but that should not be confused with giving children access to an adult mortgage account. A child might use the same household device for games or schoolwork, yet that does not make mortgage credentials or account screens appropriate for them. In my view, the age label describes the app’s general content, not the maturity required to make financial decisions.
For adults sharing a home, trust is just as important as technical access. Partners should be clear about who owns the account, who checks it, and how information is communicated. That is especially important after a separation, during a move, or whenever household finances become complicated. The app cannot resolve those relationship or legal boundaries; it only makes account information easier for the authorized user to reach.
I would also avoid using another person’s phone as a permanent workaround. If one adult needs regular responsibility for the mortgage, the cleaner approach is to establish the correct account arrangement rather than relying on a saved password or informal access. This is one of the places where a dedicated mortgage app is less flexible than a shared household spreadsheet, but that limitation is appropriate because privacy should not be traded away for convenience.
For older relatives who help with household finances, the app may be useful if they are comfortable with mobile account management. The interface needs to be judged in practice on the person’s device and habits, not assumed to be effortless for everyone. I would sit with them during the first use, explain what the account is for, and make sure they know when to stop and ask the borrower or lender for clarification.
Trust also affects notifications and phone security. I would not assume that every alert is suitable for display on a lock screen in a shared household. The safest routine is to protect the device, review what appears publicly, and close the app after use. These are ordinary precautions, but they matter more when the information concerns a home loan rather than a casual shopping account.
What the current version adds to the decision
The current version is 10.35.0, and the app has been available since August 6, 2011. That long presence gives it the feel of an established mortgage companion rather than a newly launched experiment. I still would not install it solely because it has been around for a long time; the real question is whether you already have a Rocket Mortgage relationship and want mobile access to manage it.
The minimum operating system is 10, so device compatibility should be checked before planning around the app. For households with an older phone or a shared device that does not receive regular system updates, this can become a practical obstacle. A person may be willing to use the app but still need another route to manage the mortgage if the device cannot run the required software.
One useful habit is to treat updates as part of account maintenance. When a finance app changes version, I would not rush into a major transaction immediately afterward. I would first open it, confirm that the expected account information is available, and make sure the household’s usual workflow still makes sense. That is not a criticism of this particular release; it is simply a sensible approach for any app connected to important finances.
The developer is Rocket Mortgage, which makes the app most relevant to people already dealing with that mortgage provider. If your loan is held elsewhere, downloading it just to explore a mortgage app would not make much sense. In that situation, your lender’s own mobile service or a general finance tool is likely to be the more appropriate option.
Where the app fits—and where it does not
I would recommend Rocket Mortgage to a borrower who wants a direct mobile way to stay connected with a Rocket Mortgage account, especially when the household needs quick access during budgeting or planning conversations. It is also a reasonable choice for someone who dislikes waiting for a desktop session just to orient themselves around the mortgage.
I would be more cautious if your priority is complete household financial management. The app is not the right replacement for a budget planner that combines every account, nor would I choose it as the sole record for long-term financial planning. A mortgage is one large part of a household’s finances, but it is still only one part.
I would also skip it as a shared family app. The better use is one authorized adult managing the account and communicating the relevant information to others. That arrangement may require a little more coordination, but it avoids turning a sensitive login into a communal household password.
For someone comparing it with a browser, I would choose the app for convenience and quick account awareness, then use a larger screen or direct support when the issue becomes detailed. For someone comparing it with a bank app, I would choose Rocket Mortgage when the mortgage relationship is the focus and the bank app when seeing the entire financial picture matters more.
My final view is positive but measured. The free price removes an obvious barrier, and the strong 4.7 average alongside more than a million installs shows that many people find the service useful. Still, the best experience depends on disciplined account boundaries. Use it as a secure mortgage window for the responsible adult, not as an unrestricted household screen.
That is why I would recommend it to a friend who already has a Rocket Mortgage account and wants a practical mobile routine. I would tell them to set it up on a protected device, decide in advance how the household will share information, and keep complex decisions separate from quick checks. Used that way, Rocket Mortgage makes mortgage coordination easier without pretending to be a complete family finance system.
FAQ
What is Rocket Mortgage, and what can I do with the app?
Rocket Mortgage is a mobile mortgage platform for researching home loans, checking potential rates, starting an application, uploading documents, and tracking loan progress. After signing in, you can usually review requested tasks, communicate with loan specialists, access disclosures, and monitor milestones. The exact tools available may depend on your location, loan type, application stage, and whether you are a new or existing Rocket Mortgage customer.
Can I apply for a mortgage entirely through Rocket Mortgage?
The app is designed to support a largely digital mortgage process, allowing you to provide personal and financial information, authorize verification, submit documents, and follow application updates from your phone. However, a completely hands-off experience is not guaranteed. Some applications may require additional documentation, clarification, phone conversations, property information, or in-person services depending on underwriting requirements and local regulations.
Is Rocket Mortgage safe to use for personal and financial information?
Rocket Mortgage uses account security measures and encrypted connections intended to protect information transmitted through its digital services. Even so, no online platform is completely risk-free. Download the official app from a trusted store, verify the publisher, use a strong unique password, enable available security features, and avoid entering mortgage information on public or unfamiliar networks. Always review permissions and privacy terms before continuing.
Does using the Rocket Mortgage app guarantee approval or show my final interest rate?
No. Any rates, payment estimates, or eligibility information shown in the app are generally subject to verification, credit review, loan-program requirements, property details, market conditions, and other underwriting factors. An initial estimate is not the same as final approval or a binding loan offer. Before making financial decisions, read the official disclosures carefully and confirm terms directly with Rocket Mortgage.
What should I prepare before downloading and using Rocket Mortgage?
Prepare accurate information about your income, employment, debts, assets, monthly expenses, and the property you may purchase or refinance. You may also need identification, tax documents, pay statements, bank statements, and permission for credit or financial verification. A stable internet connection and a supported device are helpful. Because mortgage decisions are significant, compare available offers and understand fees, rates, and repayment obligations.


